Alpha research, end to end.
Alpharium is an expression-driven quantitative research platform. Write a signal as a formula, backtest it across equity, futures and crypto universes, and promote it through in-sample / out-of-sample gates into a production portfolio.
Production alphas
Taiwan equities · ensemble (all-cap)
TW Equities2015-01-05 → 2026-10-05
Sharpe
2.82
Ann. return
11.3%
Max drawdown
-4.0%
Taiwan equities · ensemble (top 200)
TW Equities2015-01-05 → 2026-10-05
Sharpe
2.68
Ann. return
17.4%
Max drawdown
-7.5%
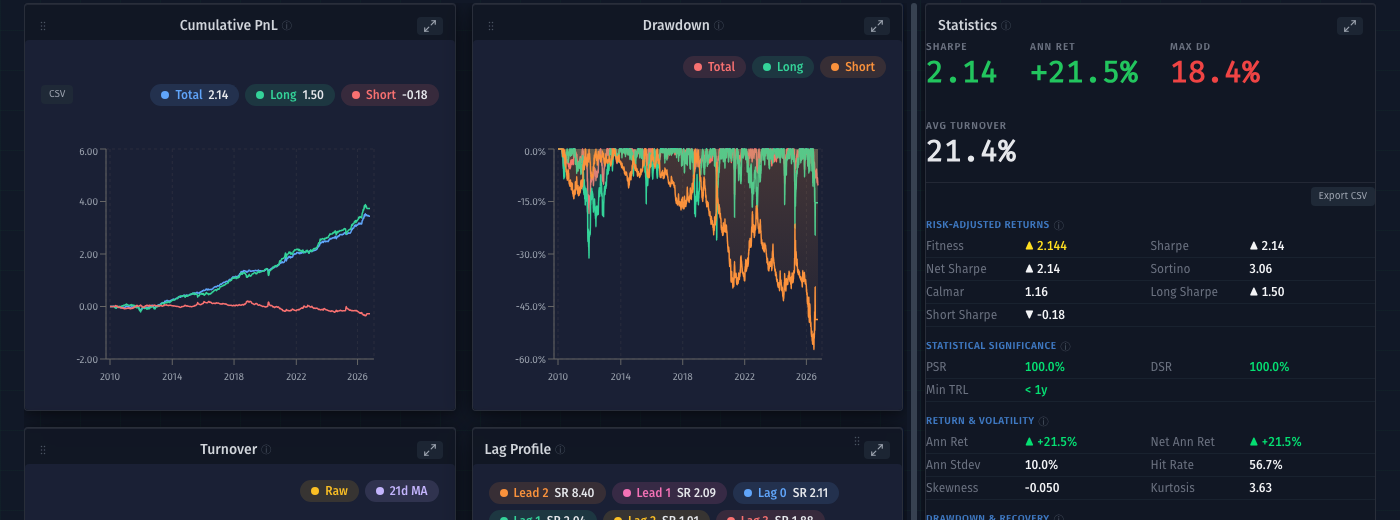
Taiwan equities · single signal (top 50)
TW Equities2010-01-04 → 2026-10-05
Sharpe
2.11
Ann. return
21.1%
Max drawdown
-18.4%
Crypto perpetuals · cross-sectional (top 30)
Crypto Perps2025-08-02 → 2026-10-05
Sharpe
1.52
Ann. return
23.1%
Max drawdown
-16.5%
How research works
1. Express
Compose signals from a rich operator library over point-in-time data.
2. Validate
IS/OOS gates, Monte-Carlo and regime analysis before anything goes live.
3. Promote
Lifecycle tracking, knowledge graph and portfolio construction in one place.
Illustrative example — not a production signal
LongShortBalance(CsDemean(CsRank(TsMean(pv_ret, 20))))
Platform
Agentic research loop
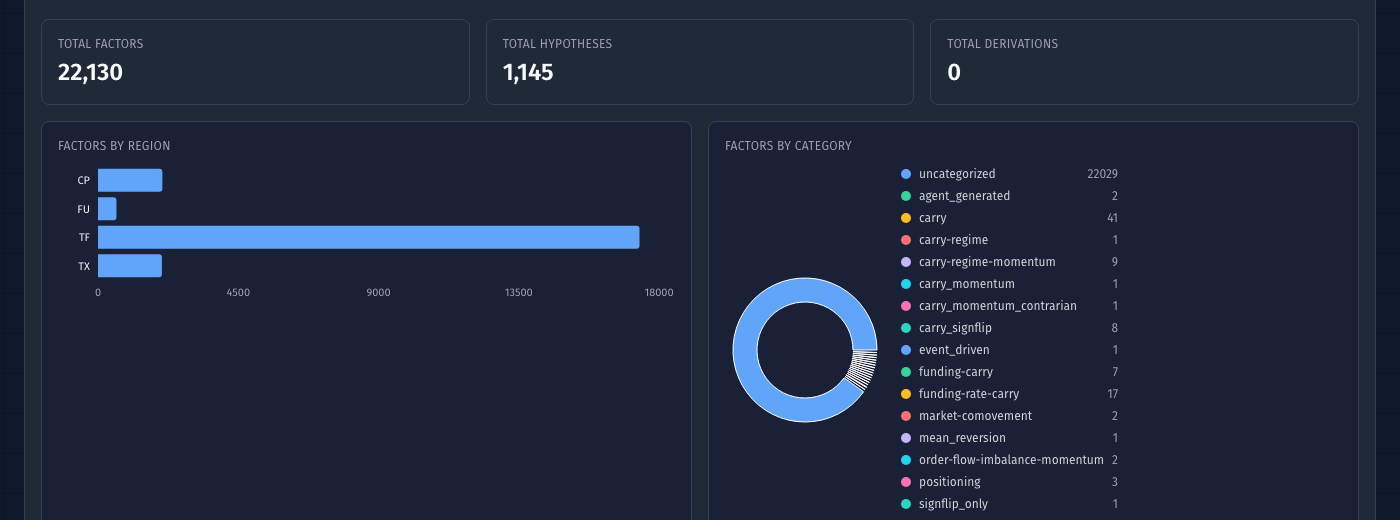
Alpharium runs research as a loop, not a one-off. Autonomous research agents generate hypotheses, submit backtests through our MCP server, read the results and iterate, recording every generation to a shared research memory so later runs start from what earlier ones learned. Humans set the research agenda and gates; agents do the volume. The same agent tooling drives most of our engineering workflow, from implementation and review to deployment and operations.
Hypothesis generation
Agents propose candidate signals from data catalogs, prior results and anti-pattern lists.
Backtest via MCP
Every experiment runs through the same batch tooling and IS/OOS gates as a human researcher.
Research memory
Findings, failures and friction are written back so the next generation does not repeat them.
About
Alpharium is a quantitative research company founded in 2026 in Taipei, Taiwan. A small team of quant researchers and engineers builds and operates the platform, running systematic strategies across Taiwan equities, index futures and crypto perpetuals. The production alphas above are live in our own portfolio; the research behind them stays private.
- Founded
- 2026
- Headquarters
- Taipei, Taiwan
- Stage
- Bootstrapped
- Contact
- [email protected]
- Profile
- Crunchbase